Money and paperwork
His, hers and ours: setting up shared finances as a couple
A practical way to set up shared money as a couple: three pots, a fair rule for contributions, a monthly check-in and scripts for the awkward moments.
By the Bloom team12 min readUpdated November 6, 2026
Sources checked on November 5, 2026
In this article
- Three ways couples organize money, and what each one costs
- Have the money conversation before you open any account
- Set up the three pots
- Choose a rule for what each person contributes
- Put it in motion and make it automatic
- Hold a twenty-minute money meeting each month
- Where the baby fits in your pots
- Words for the awkward moments
You and your partner are about to share far more than a home, and the money question usually arrives as a small, awkward one: whose card pays for what? If you are planning a baby, the question gets bigger, because the household will soon carry costs neither of you has priced yet and perhaps a change in who earns what. This article gives you a way to set up shared money that does not require you to merge everything or keep everything apart: three pots, one fair rule, and a short monthly meeting.
Three ways couples organize money, and what each one costs
There is no single correct arrangement. What matters is that you chose it on purpose, together, and that it still feels fair when circumstances change. Most couples land on one of three models, and each one trades something for something else.
Everything together
- All income goes into shared accounts and every cost comes out of them
- Very simple to run and to explain
- Needs a high level of trust and similar habits
- Small purchases can start to feel like they need approval
Works best when your spending styles are close and you both enjoy looking at the numbers.
Everything separate
- Each person keeps their own money and pays an agreed share of each bill
- Strong sense of independence
- Many small transfers and a lot of "who owes whom"
- Hard to save together, because nothing belongs to both
Works for shorter or newer arrangements, but gets heavy once there are shared goals.
His, hers and ours
- A shared pot for household costs and shared goals
- A personal pot each, spent without justification
- A rule decides what each person adds
- Needs a little setup and one regular meeting
The best balance of teamwork and autonomy for most households, and the model the rest of this article builds.
Have the money conversation before you open any account
Accounts are the easy part. The harder part is that each of you arrives with a different history with money: one of you may have grown up saving every spare coin, the other may see money as something to enjoy while it is there. Neither is wrong, but a system built on only one of those views will quietly irritate the other person. If you want a fuller guide to this first talk, read how to talk about money before a baby.
A few habits from the Better Health Channel's guidance on communication help here: set aside time without distractions, say what you need using "I" statements, let your partner finish, and aim to understand each other rather than win. If the conversation gets heated, take a break and come back to it. Money talks go better when they are scheduled and short than when they are triggered by a bill.
- 1
Pick a calm moment and a time limit
Forty-five minutes at the kitchen table beats a late-night talk in the middle of a disagreement. Agree in advance that nothing is decided at this first meeting except what to look at next.
- 2
Each person lists their own picture
Without comparing yet, each of you writes down your regular income, your fixed commitments and any debts or savings you already have. Being honest here is the whole point. Do not judge what you read.
- 3
Name what you want the money to do
A home that feels secure? Time off? A cushion? Travel? Write three goals each, then circle the ones you share. Those become the purpose of the shared pot.
Set up the three pots
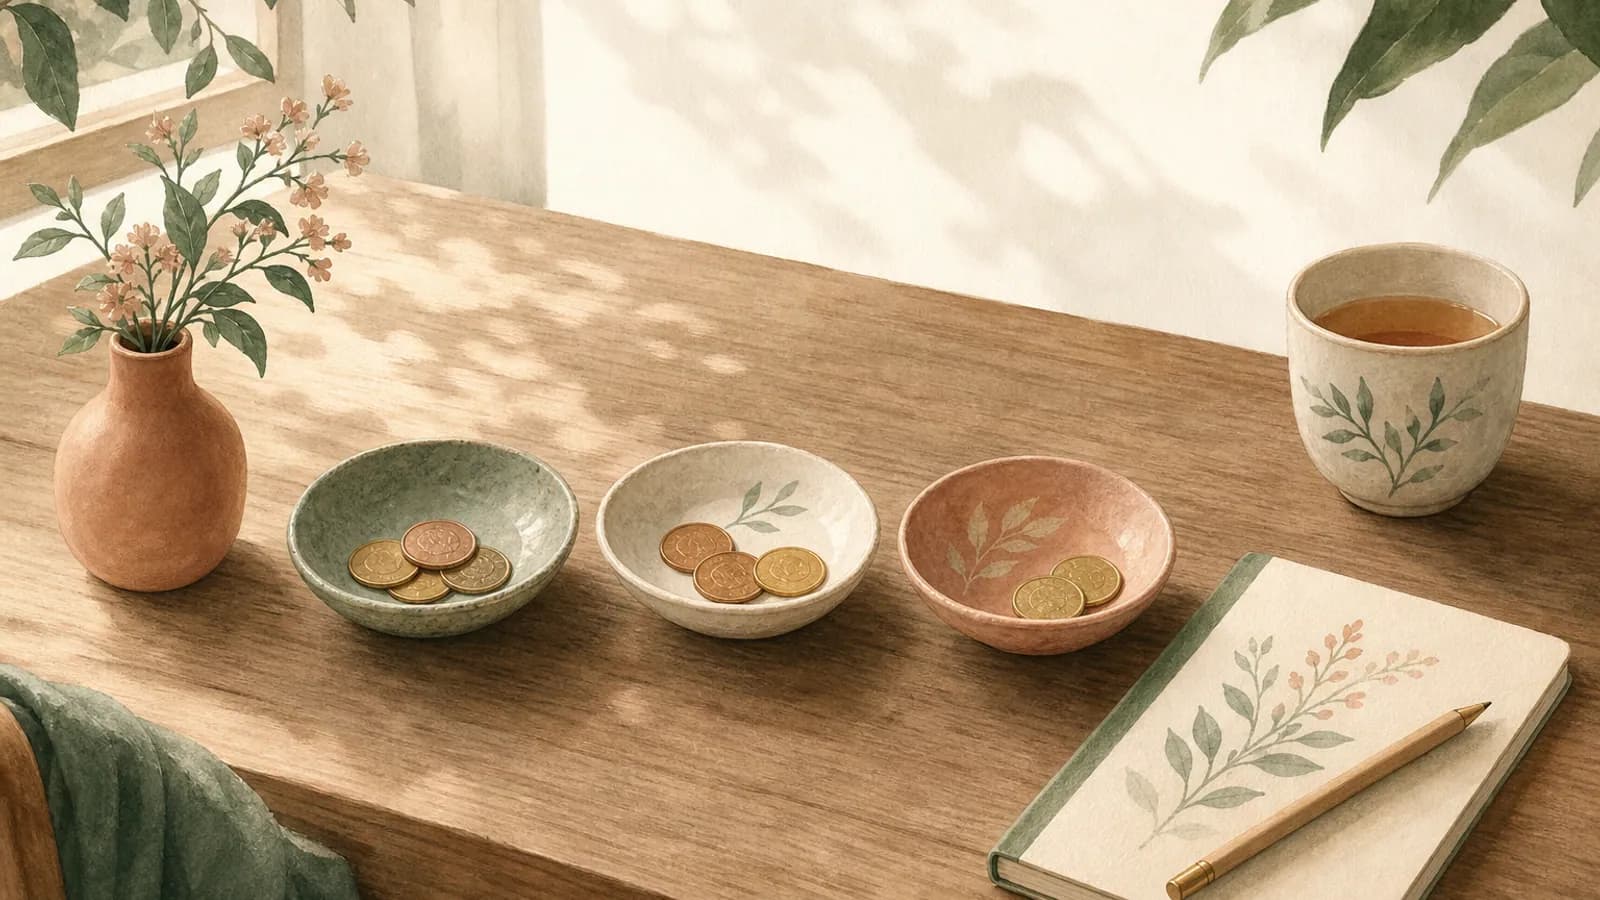
The structure is deliberately plain. You need one shared pot for the household, one shared pot for the future, and a personal pot for each of you. Depending on your bank, a pot can be an account, a sub-account or just a labelled savings goal; the name matters less than the job it has.
| Pot | Who controls it | What goes in | What comes out |
|---|---|---|---|
| Household (ours) | Both, visible to both | The agreed monthly contribution from each person | Rent or mortgage, food, utilities, transport, subscriptions |
| Future (ours) | Both, two-person decisions | A fixed amount each month, first thing | Cushion, big purchases, baby costs, shared plans |
| Personal (yours) | You alone | A set amount, same logic for both | Anything, with no explanation owed |
| Personal (theirs) | Your partner alone | A set amount, same logic for both | Anything, with no explanation owed |
Keep the personal pots equal in size or on the same percentage, so neither person feels they are borrowing from the other.
The personal pot is the part couples most often skip, and it is the part that keeps the system peaceful. When each person has money they can spend freely, the small stuff stops being a negotiation: a gift, a hobby, a coffee that was not on the plan. It also makes surprises possible.
The household pot only needs to cover recurring costs, so it is easy to check: if its balance trends down, the contributions are too low; if it keeps growing, move the extra into the future pot. The future pot is where a cushion starts. The consumer-finance guide to building an emergency fund suggests choosing a specific savings goal, saving consistently even in small amounts, and setting up recurring transfers so it happens without effort. That advice transfers directly to a couple's future pot.
Choose a rule for what each person contributes
This is the step where most couples either argue or avoid. The way out is to decide on a rule, not on a number, so that you only need to agree once and the result updates itself when incomes change. There are two common rules.
- Equal amounts. Each person adds the same sum to the household pot. It is simple, and it fits when your incomes are close.
- Proportional shares. Each person adds the same percentage of their income, or covers the same share of shared costs as their share of the combined income. It fits when incomes differ, because both people give up the same fraction of what they earn.
Here is a worked example with fictional round numbers in currency units. Say the shared costs of the household are 2,000 a month. One partner earns 3,000 and the other 1,000, which makes 4,000 combined.
| Rule | Partner A adds | Partner B adds | Left for A | Left for B |
|---|---|---|---|---|
| Equal amounts | 1,000 | 1,000 | 2,000 | 0 |
| Proportional (75% / 25%) | 1,500 | 500 | 1,500 | 500 |
Example only. Under equal amounts, partner B has nothing left; under proportional shares, both keep the same fraction.
Neither rule is automatically right. The research summary in the Greater Good Science Center's article on an unfair division of labor is about household work rather than money, but it makes a point that applies here too: what matters is that the arrangement feels fair to both people, and talking about it openly helps. Fair does not have to mean identical.
When one income changes
A baby can change how much each person earns or works, for a while or for good. Decide the answer before it happens, while nothing is at stake: does the rule stay the same, switch to proportional, or does the household pot get topped up from the future pot for a set number of months? You do not need to solve it now; you need to agree when you will talk about it.
Put it in motion and make it automatic
- 1
List the shared costs
Go through three months of statements and write down every recurring cost that serves you both. Add the irregular ones (annual fees, repairs, gifts) as one-twelfth of their yearly total.
- 2
Apply your rule
Work out each person's contribution with the worksheet below. Round to a number that is easy to set up.
- 3
Open or label the pots
Create the household pot, the future pot and one personal pot each, or label existing accounts. Make both people able to see the shared ones.
- 4
Automate the transfers
Set standing transfers for the day after each payday: contribution to the household pot, then the future pot, then each personal pot. When money moves without a decision, there is nothing to argue about on the day.
- 5
Put a date in the calendar
Choose the day of the monthly meeting and a date, six months ahead, to review the rule itself.
| Item | Per month | Paid from | Owner |
|---|---|---|---|
| Housing | Household | ||
| Food and household supplies | Household | ||
| Utilities and internet | Household | ||
| Transport | Household | ||
| Subscriptions and memberships | Household | ||
| Irregular costs, yearly total divided by 12 | Household | ||
| Future pot contribution | Future | ||
| Personal pot, partner A | Personal | A | |
| Personal pot, partner B | Personal | B |
Add up the household lines to get the monthly target, then split it with your rule. The Owner column names who watches that line.
Hold a twenty-minute money meeting each month
A system with no review slowly drifts. A short, regular meeting keeps small problems small and makes money a normal topic, not an emergency one. Keep it brief, hold it at the same time each month, and put it somewhere pleasant: with food, not in the middle of dinner and not after a hard day.
Agenda for the monthly meeting
Look back (5 minutes)
- Did the household pot cover its bills? Note the balance
- Did every automatic transfer happen?
- Anything unexpected that cost more than planned?
Look ahead (10 minutes)
- Known costs for the next month: trips, gifts, renewals
- Anything to move from the household pot to the future pot
- Progress on the shared goal, in whatever unit you track it
Decide and close (5 minutes)
- One decision made, with a name and a date next to it
- One thing each of you appreciated about how the other handled money this month
- Date of the next meeting
Ending with an appreciation keeps the meeting from feeling like a performance review. For tracking what a new baby costs once it begins, a simple shared list is enough; a ledger for baby expenses shows how to keep one without it taking over your evenings.
Where the baby fits in your pots
You do not need a separate system for a baby. You need one new line in the future pot and one habit. Name a goal inside the future pot ("baby start-up") and give it a monthly amount you can keep up.
- Before the baby arrives: use the future pot for the one-off things, and decide together which of them you will buy new and which you will find through friends, swaps or second-hand. The article on borrowing, swapping and buying second-hand has a method for that choice.
- After: costs become recurring. Add a new line to the household worksheet and look at it at the monthly meeting for the first few months, because actual costs will differ from your estimate.
Words for the awkward moments
Even with a good system, some moments are difficult. Having a sentence ready makes them shorter. These are suggestions to adapt into your own voice.
| Situation | A way to say it |
|---|---|
| You want to spend from the shared pot | "I would like to use some of our future pot for this. Can we look at it together on Sunday?" |
| Your partner spent from a personal pot on something you would not choose | "I notice I have an opinion about this, but it is your pot. Thank you for telling me." |
| One of you has a debt or a past mistake to disclose | "There is something I want to tell you, so we can plan with the full picture. I am nervous, and I would like us to look at it as a team." |
If your partner is less ready to talk about the future than you are, money can feel like pressure. One of you is ready and the other is not covers how to pace those conversations without turning them into a standoff.
None of this has to be perfect on the first day. A plain system that you both understand and actually use will do more for you than a clever one that lives in one person's head. Start with the pots, write the rule, put the meeting in the calendar, and adjust as you learn how the two of you really spend.
Should we merge all our money after moving in together?
There is no obligation to. Many couples keep a shared pot for the household and the future and a personal pot each, because it combines teamwork with independence. If you do choose to merge everything, do it because you both want to, not because it seems the normal next step.
Is it better to split costs equally or in proportion to income?
Equal amounts are simple and suit similar incomes. Proportional shares keep the burden comparable when incomes differ. A useful test is to look at what each person has left after the contribution: if the gap feels unfair to either of you, change the rule.
How much should each personal pot be?
Enough that neither person has to justify small purchases, and the same size or the same percentage for both. Start with a modest amount and adjust at the six-month review.
How often should we change the setup?
Review the rule every six months and whenever something large changes, such as a new job, a move or a baby on the way. The monthly meeting is for running the system, not for rewriting it.
These are suggestions to help you organize, not medical advice. Your professional decides what's relevant for you. How we write and check our articles
Sources
Checked on November 5, 2026. We link to the official pages instead of copying them.
- Better Health Channel. Relationships and communication
- Greater Good Science Center. How an unfair division of labor hurts your relationship
- Consumer Financial Protection Bureau. An essential guide to building an emergency fund